
Swiss and cross-border tax advice for tech companies, from the first share issued to the exit
Employee equity plans, financing rounds, international structuring and corporate tax, handled by a Swiss Certified Tax Expert (dipl. Steuerexperte) who works hand in hand with your LEXR lawyers.



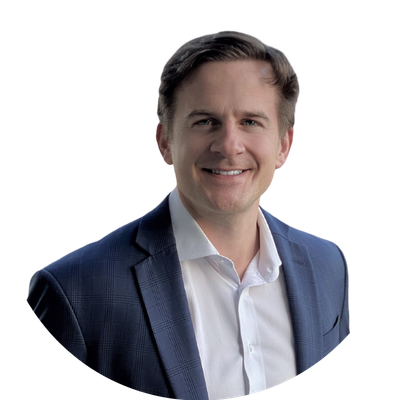
"Planning an equity plan, a financing round or a move to the US? Book a call with me. We have helped tech companies settle employee equity, founder shares and international structures with the tax authorities, and we tell you early what will be taxed and when."
Silvan Amberg · Tax Counsel at LEXR, Swiss Certified Tax Expert (dipl. Steuerexperte) · Get in touch →
Meet the tax team
* not registered at the bar
Why LEXR for tax
Tax and legal in one team
The shareholders' agreement, the equity plan and the tax ruling are drafted together, not by two advisers who never spoke. Tax work is done by our Swiss Certified Tax Expert, legal work by our lawyers, and the line between the two is always clear.
The ruling before the transaction
An advance tax ruling is the cantonal tax authority confirming your treatment in writing before you act. For employee equity and founder shares this is often the step that gives employees, investors and auditors certainty. We prepare the submission and the analysis behind it.
Tax advice that speaks tech
Our tax counsel is a Swiss Certified Tax Expert (dipl. Steuerexperte) who regularly files equity plan rulings with the tax authorities in Zurich and Zug and knows how each of them reads a plan. You do not have to explain what a vesting period, a convertible or a Delaware parent is.
What we offer
Restricted stock, restricted stock units, options and phantom plans. We value the shares, calculate the discount for vesting periods, qualify the plan as genuine or non-genuine employee participation and secure the treatment with an advance ruling. We also cover payroll, social security and withholding questions for employees in several cantons or countries.
Founding structure, vesting and leaver clauses, share transfers between founders and the company, dynamic equity splits, and convertible loans and SAFEs. We make sure that what founders and early employees receive is taxed as planned.
Tax review of a priced round, secondary sales, a flip to a US parent and the sale of the company. We look at both sides: the company, and the founders and employees who sell.
Intercompany service, IP and cost-sharing agreements with a foreign parent or subsidiary, permanent establishment risk for team members working abroad, and withholding tax on cross-border payments. A Swiss company with an international team needs prices and contracts that hold up to an audit.
Tax returns, advance rulings, VAT registration, reverse charge on services bought from abroad, and the tax treatment of grants, R&D and IP income.
Crypto and blockchain projects, and financial services (asset managers, funds, banks and family offices).
Tax solutions for blockchain projectsHow we work
Five steps, the same for an equity plan, a financing round or a cross-border setup.
-
Free intro call
You tell us what is planned. We tell you what matters for tax and whether a ruling is worth it.
-
Fixed scope and fee
We agree on what we deliver and what it costs before we start.
-
Analysis
We review the documents (plan, shareholders' agreement, term sheet, intercompany contracts) and model the tax effects for the company, the founders and the employees.
-
Ruling or filing
Where a treatment should be confirmed, we draft the submission and deal with the tax authority directly.
-
Follow-up
We update the position when the plan, the cap table or the business changes, and handle the yearly valuation and filing work.
Global reach. Local roots. One team.
-
London › Zurich
UK-based bank expands its digital assets offering to Switzerland with the legal advice of LEXR
-
Zurich
LEXR advises BIT Asset Management on the SIX exchange listing of its Bitcoin ETF
-
Berlin › New York
LEXR advises a FinTech scale-up on their Delaware flip to expand to the US market
-
Brussels › Zurich
LEXR structures a tokenized tracker certificate and drafts EU prospectus for retail distribution
FAQs
It depends on the instrument. Restricted shares are generally taxed when they are granted, after a discount for the vesting period. Options are generally taxed when exercised, and units or phantom plans when they are paid out in cash. The federal circular on employee participations sets the framework, and each canton applies it with its own practice.
Not legally, but it is usually worth it. A ruling confirms how the company values the shares and how employees are taxed, which gives investors, auditors and employees certainty. Plan on several weeks, depending on the canton and how complete the first submission is.
The tax effect of moving the shares to a US parent, the valuation used, the position of founders who stay in Switzerland, the treatment of employee equity after the flip, and the new intercompany arrangements between the parent and the Swiss company. We review these together with the legal steps.
Services and IP that stay in Switzerland need an arm's length price, written down in an agreement. The tax authority looks at who actually does the work and who carries the risk. A well documented arrangement is far easier to defend than one built after the fact.
Once its taxable turnover passes the legal threshold, and in some cases earlier. Registration can fall in the first year of operation, and a late registration can leave VAT unrecoverable. Services bought from abroad can trigger reverse charge VAT even before that.
When a Swiss business buys services from a foreign supplier, the Swiss recipient owes the VAT, not the supplier. No invoice carries Swiss VAT, so nothing prompts the entry. Where the company is registered and entitled to input tax, the same amount is often recoverable, so the task is to declare it correctly.
